Learning how to set financial goals is one of the most powerful things you can do for your future. Most people want more money, less stress, and a little more freedom, yet few ever write down what that actually looks like. Without clear targets, money disappears into daily spending, and months turn into years without real progress. The good news is that you don’t need a high income or a finance degree. You need a clear direction, a realistic plan, and a few habits you can repeat. In this guide, you’ll learn a simple process to choose goals that matter, put numbers on them, and build a plan you can actually follow.
Why Financial Goals Matter More Than You Think
Money without a purpose rarely stays where you want it. A financial goal gives every dollar a job, which makes it easier to say no to impulse spending and yes to the things that move your life forward. The Consumer Financial Protection Bureau offers free tools built around the idea that planning ahead is a core part of financial well-being.
Clear goals do three powerful things:
- They create focus. You stop guessing where your money should go.
- They reduce stress. You know you’re working toward something specific.
- They make progress measurable. Seeing the numbers move keeps you motivated.
That is exactly why learning how to set financial goals is worth your time, whether you earn a modest salary or a large one.
How to Set Financial Goals: Start With Your “Why”

Before you pick a number, ask a bigger question: what do you want your money to do for you? The most effective approach to how to set financial goals begins with emotion, not math. A goal like “save $10,000” feels empty. A goal like “build a cushion so I never panic about rent again” feels personal, and personal goals are the ones you stick with.
Take ten minutes and write down your answers to these prompts:
- What would make me feel financially secure?
- What do I want to be able to afford in one, five, and ten years?
- What am I tired of worrying about?
Your answers reveal your real priorities. Maybe it’s escaping debt, buying a home, starting a business, or retiring comfortably. Whatever it is, name it clearly. That “why” will carry you through the months when motivation fades.
Take Stock of Your Current Financial Situation
You can’t plan a route without knowing your starting point. Gather your bank statements, pay slips, loan balances, and credit card bills, then calculate three numbers:
- Monthly income: everything you reliably earn after tax.
- Monthly expenses: fixed bills plus everyday spending.
- Net worth: what you own minus what you owe.
If you’ve never tracked your spending, do it for 30 days. Most people are surprised by how much leaks out through subscriptions, takeout, and small purchases. Our guide on how to create a budget that works walks you through the process step by step. Honest numbers, even uncomfortable ones, give you a foundation you can build on.
How to Set Financial Goals With the SMART Method
The SMART framework is the simplest answer to how to set financial goals you will actually reach. Each goal should be:
- Specific: Say exactly what you want. “Save for a house deposit” beats “save more.”
- Measurable: Attach a number, such as $15,000.
- Achievable: Match the goal to your income and obligations.
- Relevant: Make sure it supports your “why.”
- Time-bound: Set a deadline, such as 24 months from now.
Here’s an example. Instead of “I want an emergency fund,” a SMART version reads: “I will save $6,000 for emergencies by December 2027 by setting aside $300 every month.” Notice how that single sentence tells you what to do, how much, and by when. There’s no room for confusion, and that clarity is what turns a vague wish into a target you can hit.
Short-Term, Medium-Term, and Long-Term Goals

Once you understand how to set financial goals, sort them by timeline so you can prioritize:
- Short-term (under 1 year): a starter emergency fund, clearing a small debt, saving for a trip.
- Medium-term (1 to 5 years): a car, a wedding, a house deposit, a business launch.
- Long-term (5+ years): retirement, your children’s education, financial independence.
Don’t try to chase everything at once. Pick one or two goals per timeline and rank them. A sensible order for most people is a starter emergency fund first, then high-interest debt, then a larger emergency fund, and finally long-term investing. Your situation might differ, and that’s fine. The point is to choose deliberately rather than react to whatever feels urgent.
Build a Step-by-Step Plan to Reach Your Goals
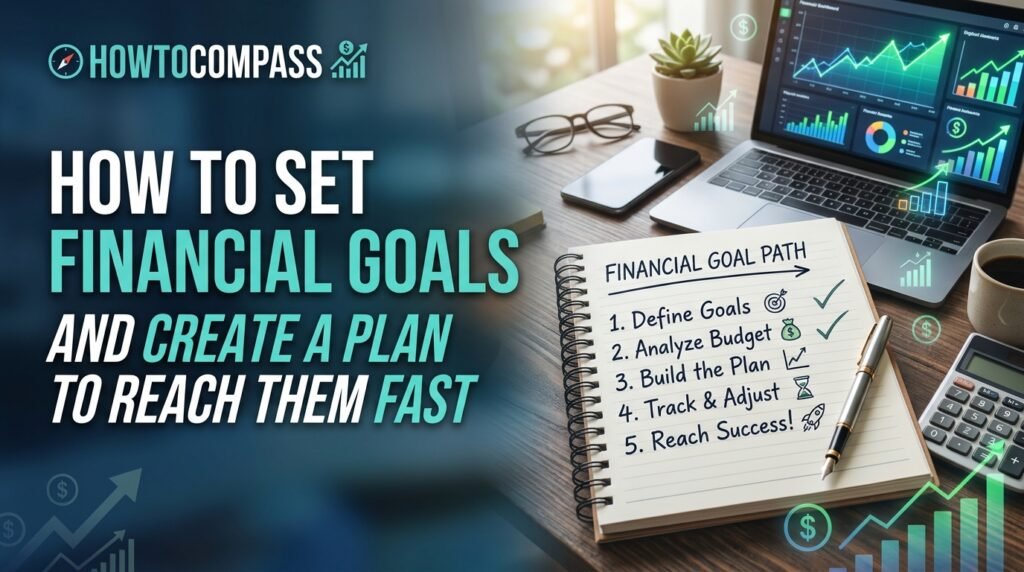
A goal without a plan is just a wish. Here’s a simple process to turn your targets into action:
- Break each goal into monthly amounts. Divide the target by the number of months. If you need $6,000 in 20 months, that’s $300 a month.
- Automate your savings. Schedule transfers for payday so the money moves before you can spend it.
- Build your safety net first. Aim for three to six months of essential expenses, as explained in this Investopedia guide to emergency funds.
- Attack high-interest debt. Pay the minimum on everything, then throw extra cash at the highest rate. Our article on how to pay off debt fast covers two proven methods.
- Invest for the long term. Time is your biggest advantage, and the compound interest calculator at Investor.gov shows how small, regular contributions grow over the years.
- Review monthly. Spend 15 minutes each month comparing your progress to your plan and fixing anything that has drifted.
The plan is the bridge between knowing how to set financial goals and actually achieving them. Without it, even the best goal stays on paper.
Common Mistakes When You Learn How to Set Financial Goals
Even motivated people trip up. Watch out for these:
- Being vague. “Be better with money” can’t be measured or finished.
- Setting too many goals. Spreading your cash thin means nothing gets completed. Focus on two or three.
- Ignoring irregular expenses. Car repairs, medical bills, and holidays will happen. Build them into your plan.
- Setting unrealistic deadlines. An impossible target leads to quitting. Be ambitious but honest.
- Never reviewing. A plan you don’t check is a plan you’ll abandon.
- Skipping the celebration. Rewarding milestones, even with something small, keeps you in the game.
Avoiding these mistakes is half the battle when you’re mastering how to set financial goals. If you’re struggling to find extra money for your plan, these easy ways to save money fast can free up cash without making life miserable.
Stay Motivated and Adjust Along the Way

Life changes, and your goals should too. A new job, a baby, or an unexpected bill can shift your priorities overnight. Treat your plan as a living document. Review it every quarter, and don’t see changes as failure. Knowing how to set financial goals also means knowing when to revise them.
A few habits make the journey easier:
- Make progress visible. Use a simple chart or spreadsheet and color in each milestone.
- Share your goals. Tell a trusted friend or partner who will cheer you on and keep you accountable.
- Celebrate small wins. Paying off one card or hitting your first $1,000 deserves recognition.
- Keep your “why” in sight. Write it on a sticky note and put it where you’ll see it daily.
Final Thoughts
Now you know how to set financial goals that are clear, realistic, and tied to what matters most to you. Start with your “why,” take stock of your numbers, use the SMART method, and build a plan you can automate. You don’t have to do everything today. Pick one goal, write it in SMART format, and take the first small step this week.
Remember, how to set financial goals is a skill, and like any skill it improves with practice. Stay consistent, adjust when life changes, and keep your eyes on the future you’re building. Your future self will thank you.